Many tradespeople set their hourly rate by looking at what others charge. The problem: the competitor's costs, workload and goals are not yours. If your rate is too low, you work full weeks and still have nothing left at the end of the month. Here is a simple method to calculate an hourly rate that really covers your business.
In short
- Add up all monthly business costs and the salary you want to pay yourself.
- Count only billable hours - usually 60-70% of your working time.
- Divide costs by billable hours and add a profit margin of 10-20%.
- Check the result every few months against your real numbers.
Step 1: Add up your monthly costs
Write down everything the business pays in an average month, even if some costs come yearly (divide them by 12):
- Van or car: leasing, fuel, insurance, service
- Tools and equipment, including replacement and repairs
- Business insurance and liability insurance
- Workshop or storage rent
- Phone, internet, software, accountant
- Advertising, website, work clothes
- Social contributions and taxes you pay as the owner
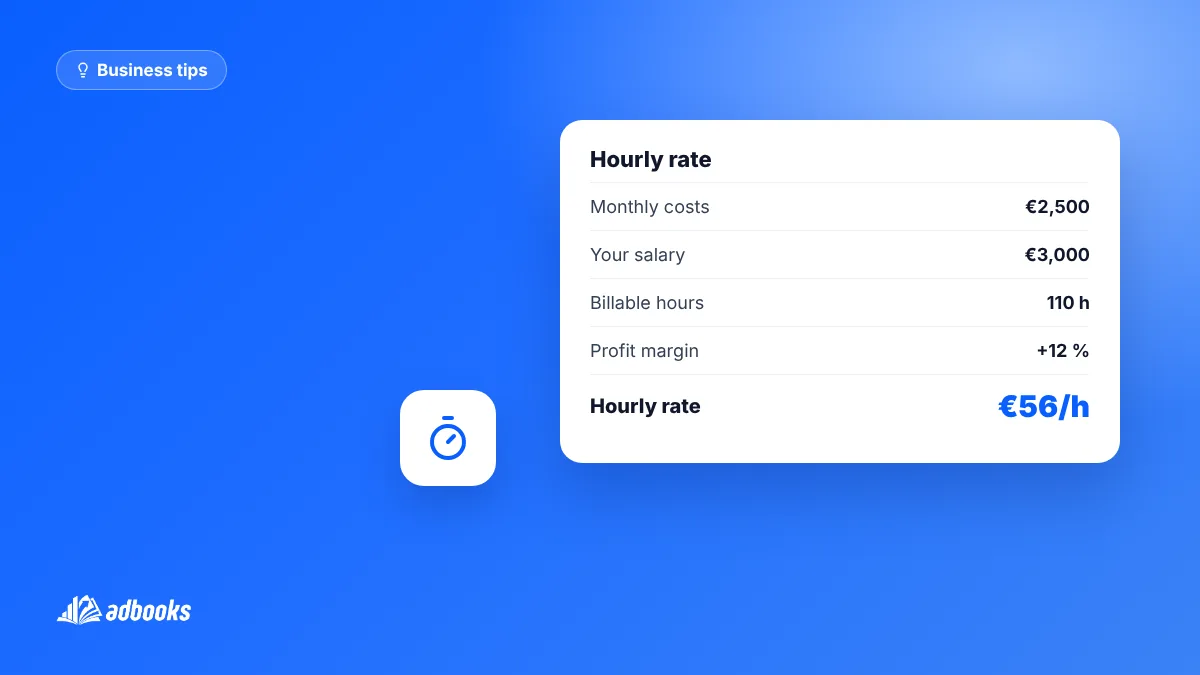
Example: a one-person company has 2,500 € of monthly costs.
Step 2: Decide what you want to earn
Your salary is a cost of the business, not what is "left over". Decide what gross amount you want to pay yourself every month - including holidays and sick days. Example: 3,000 € per month.
Together with costs, the business must earn 5,500 € per month.
Step 3: Count your real billable hours
This is the step most people get wrong. A month has about 21 working days of 8 hours, so 168 hours. But not all of that can be billed. You also spend time on:
- Driving between jobs and to suppliers
- Writing quotes and invoices, phone calls with clients
- Measuring, planning and buying materials
- Waiting, cleaning up, fixing complaints
For most tradespeople, only 60-70% of the time is billable. With 65%, that is about 110 billable hours per month.
Step 4: Calculate the rate
Divide what the business must earn by billable hours:
5,500 € / 110 h = 50 € per hour
That is your break-even rate: you cover all costs and your salary, but there is no money for growth, new tools or a bad month.
Step 5: Add a profit margin
Add 10-20% on top so the business can grow and survive quiet months. With 12%: 50 € x 1.12 = 56 € per hour. That is your minimum hourly rate. If the market allows more - for urgent jobs, specialised work or excellent reviews - charge more.
Tip: keep your costs, hours and invoices in one place, so you can recalculate in minutes. Try AdBooks free for 14 days and see income, expenses and profit per project.
Hourly rate or fixed price?
Even if you quote a fixed price for a job, the hourly rate is your basis. Estimate the hours, multiply by your rate, add materials with a buffer - and you know whether the fixed price pays off. After the job, compare the estimate with the real hours. In AdBooks, worker hours, expenses and income are recorded per project, so you see the real margin of every job.
How to raise your prices without losing clients
- Raise prices for new clients first, existing clients later.
- Announce the change in advance and explain it briefly (materials, fuel, wages).
- Show value: fast quotes, clean work, reliable deadlines.
- Raise prices a little every year instead of a big jump every five years.
Frequently asked questions
What if my calculated rate is higher than the competition?
Check your billable hours first - often there is more room there than in the price. If the rate is still higher, compete on quality, speed and reliability, not only on price. Clients who choose only by price rarely stay loyal.
Should materials have a margin too?
Yes. Ordering, picking up, storing and guaranteeing materials costs time and money. A margin of 10-15% on materials is common in many trades.
How often should I recalculate my rate?
At least once a year, and whenever a large cost changes - a new van, an employee or higher insurance.
Does this work for a company with employees?
Yes, the principle is the same: add up all costs including wages, and divide by the billable hours of the whole team.
Conclusion
Your hourly rate is not a guess - it is a calculation. Add up costs and your salary, count only billable hours, add a profit margin and check the result regularly. With the right rate, every job you win also makes money.